Chapter 8: Industry, Players, Careers & Learning
This chapter steps back from the equipment to look at the industry itself: how data centres make money, what they cost to build, run and finance, who the big builders, landlords and suppliers are, and where in the world the action is. It then turns to you, setting out the jobs available, the certifications employers recognise, the best free resources and how to answer common interview questions. Company facts were checked as of late 2026, but ownership and deals change fast, so always verify the latest before quoting them.
8.1 How the Data Centre Industry Makes Money
Data centres are expensive buildings that someone has to pay for, so the industry has a few standard ways of doing business. Some giant tech companies build their own, while specialist landlords build and rent space, power and cooling to others. Rent is usually charged per kilowatt (kW) of power reserved each month, because power, not floor space, is the scarce thing.
Think of it like…
It is like housing: some people build their own house, some rent a whole house built to their wishes, and some rent one flat in a big shared block with a concierge.
Real-world example
Fictional landlord Harbourline DC builds a 36 MW campus and pre-leases 24 MW to a cloud company on a 15-year contract at an illustrative $140 per kW per month. That one contract brings in about $40 million a year, which lets Harbourline borrow money to finish construction. The remaining 12 MW is sold as retail colocation to 60 smaller customers at higher prices per kW, plus monthly fees for cross-connects.
How it works
- A developer secures land, planning permission and, most importantly, a grid connection.
- It signs anchor tenants before or during construction (pre-leasing) to de-risk the project.
- Banks, REIT shareholders or infrastructure funds finance the build against those signed leases.
- Customers pay monthly rent per kW reserved, plus power used, cross-connects and services.
- Mature, fully leased buildings are often sold or refinanced to investors to fund the next project.
Who uses it
Developers, investors, brokers, sales teams and hyperscaler real-estate teams live in this world; every engineer benefits from knowing why the money flows the way it does.
Key takeaway
In interviews remember that capacity is sold in kW or MW of critical IT load, and that low vacancy plus long lead times for power equipment are what drive prices up.
Going deeper
- Wholesale deals are priced per kW of critical IT capacity per month, often with annual rent escalators of a few percent, while electricity is passed through at cost or with a margin.
- Retail colocation earns more per kW, and interconnection is its highest-margin product: each cross-connect has a one-off installation charge (NRC) and a monthly recurring charge (MRC).
- Development economics compare yield on cost with the yield buyers pay for stabilised assets; the gap is the developer's value creation, which is why leased buildings are often sold or recapitalised.
- Tenant credit quality drives financing: a 15-year lease with an investment-grade hyperscaler can support large construction loans and, later, asset-backed securities.
- Market reports track inventory (MW built), MW under construction, pre-leased share, net absorption, vacancy and asking rents, published regularly by major brokers.
- Risks include customer concentration, equipment and grid delays, technology obsolescence as rack densities jump, and refinancing costs when interest rates rise.
Common mistakes & misconceptions
- Quoting capacity in square metres; the industry prices and plans in kW and MW of critical IT load.
- Confusing contracted, built and energised megawatts; announcements often count capacity that is years from operation.
- Assuming low vacancy guarantees profit; construction delays, power costs and tenant concentration can still hurt returns.
Try it: Estimate yearly lease revenue for a building (illustrative prices only)
# Python: lease revenue = kW leased x price per kW per month x 12
leases = {
    'Cloud anchor (wholesale)': (24_000, 140),   # kW, $/kW/month (illustrative)
    'Retail colo customers':    (9_000, 260),
}
total = 0
for name, (kw, price) in leases.items():
    yearly = kw * price * 12
    total += yearly
    print(f'{name:28s} {kw/1000:5.1f} MW  ${yearly/1e6:6.1f}m per year')
print(f'Total: ${total/1e6:.1f}m per year')
print(f'Vacancy: {(36_000-33_000)/36_000:.0%} of a 36 MW building')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Self-build (owner-operated) hyperscale Cloud and internet giants · Concept · Current · Business |
A company designs, owns and runs its own data centres for its own services instead of renting. | A cloud provider builds a 300 MW campus on land it owns and staffs it with its own engineers. |
| Wholesale / build-to-suit leasing Developers such as Vantage, STACK, Aligned, CyrusOne · Service · Current · Business |
Revenue model leasing whole halls or buildings to one tenant for 10-20 years, at a lower price per kW but with predictable, financeable income. | A 48 MW lease signed before construction lets the developer raise construction debt against the tenant's strong credit rating. |
| Retail colocation Operators such as Equinix, Digital Realty, NTT DATA · Service · Current · Business |
Revenue model selling racks, cages and suites to many customers at higher prices per kW, plus recurring fees for cross-connects and services. | A provider earns more per kW from 200 small customers than from one hyperscaler, but needs sales, support and interconnection staff to do it. |
| Interconnection Carrier-neutral colocation providers · Service · Current · Business |
Selling physical cross-connects and virtual links so customers, carriers and clouds connect directly inside one building. | A retailer pays a monthly fee for a fibre cross-connect from its cage to a cloud on-ramp in the same facility. |
| Powered shell Developers and landlords · Concept · Current · Business |
Lease product where the landlord supplies land, building and grid power, while the tenant pays for and owns the expensive internal fit-out. | A hyperscaler pays lower rent on a powered shell but spends its own capital on the UPS, cooling and switchgear inside. |
| Price per kW per month Industry pricing convention · Metric · Current · Business |
Rent is quoted by reserved IT power per month; wholesale is cheaper per kW than retail colocation. | A tenant reserving 2 MW at an illustrative $150/kW/month pays about $300,000 monthly before electricity. |
| Pre-leasing Developers and anchor tenants · Practice · Current · Business |
Signing tenants before a building is finished; in hot markets most new capacity is leased years before it opens. | A campus due in 2028 is already 90% committed to two tenants while still a muddy construction site. |
| Vacancy rate Brokers such as CBRE, JLL, Cushman & Wakefield · Metric · Current · Business |
Share of built capacity not leased; in major North American markets it fell to record lows around 2% by 2025. | With almost nothing free, a startup needing 5 MW in a primary market must wait for a future building. |
| Data centre REIT US tax structure; e.g. Equinix, Digital Realty, Iron Mountain · Concept · Current · Business |
A Real Estate Investment Trust owns property and pays most profits to shareholders as dividends, getting tax advantages. | A pension fund buys shares in a data-centre REIT to earn steady dividends from long leases. |
| Private equity & infrastructure funds e.g. Blackstone, KKR, BlackRock's GIP, Brookfield, DigitalBridge · Organisation · Current · Business |
Investors that buy or fund data-centre platforms because long leases give predictable, bond-like income. | An infrastructure fund buys a regional operator, funds five new buildings, then sells or lists it years later. |
| Sale-leaseback Enterprises and investors · Concept · Current · Business |
A company sells its own data centre to an investor and rents it back, freeing cash while staying in place. | A fictional insurer sells its 4 MW site for cash and signs a 12-year lease to keep using it. |
| GPU-as-a-service (neocloud model) e.g. CoreWeave, Nebius, Lambda, Crusoe, Nscale · Concept · Emerging · Business |
Business model renting GPU clusters by the hour or on multi-year contracts, financed largely by debt and dependent on a few large customers. | An AI lab signs a three-year take-or-pay contract for 8,000 GPUs, which the provider uses to borrow money for the servers. |
| Supply-chain bottlenecks Transformer, switchgear, generator and turbine makers · Concept · Current · Electrical |
Large transformers, switchgear, gensets and gas turbines have had waits of a year to several years, slowing new builds. | A developer orders transformers before it even has planning permission so they arrive in time. |
| Net absorption Brokers such as CBRE, JLL, Cushman & Wakefield · Metric · Current · Business |
Megawatts of capacity newly leased and occupied in a market during a period, minus space given back; a key demand indicator. | A broker report shows record yearly absorption in a major market, signalling that demand is outpacing new supply. |
| Yield on cost Real-estate and infrastructure investors · Metric · Current · Business |
Annual net operating income divided by total development cost; developers compare it with market yields to decide whether to build. | A $1bn campus earning $110m a year in net operating income has an 11% yield on cost, attractive versus lower sale yields. |
8.2 Data Centre Costs, TCO & Financing
Data centres cost enormous sums to build and run. Building costs are usually counted per megawatt (MW) of IT capacity, running costs are dominated by electricity, and AI servers can cost more than the building around them. Total cost of ownership (TCO) adds everything up over the years, and financing explains where the money comes from: company cash, loans, investors and bonds.
Think of it like…
It is like buying and running a car: the price matters, but fuel, insurance, servicing and loan interest over ten years can add up to more than the car itself.
Real-world example
Fictional developer Harbourline plans a 40 MW wholesale building. At an illustrative $13 million per MW the facility costs about $520 million before any IT, plus land and grid-connection charges. It signs a 15-year triple-net lease with a cloud company, so the tenant pays power, insurance and taxes on top of rent. Banks lend most of the build cost against that lease, and once the building is full Harbourline refinances with asset-backed bonds and recycles its equity into the next campus.
How it works
- Estimate capital cost per MW for land, shell, power, cooling and fit-out, plus IT equipment if you are the user.
- Estimate yearly operating cost: electricity, staff, maintenance, insurance, taxes, water and connectivity.
- Combine them over the asset's life into TCO, using depreciation periods and a discount rate.
- Fund the build with equity, construction loans or joint ventures, usually backed by signed leases.
- Refinance stabilised buildings through long-term debt, securitisation or asset sales, and reinvest the capital.
Who uses it
Finance analysts, cost managers, development directors, investment and real-estate professionals, data-centre finance teams and the engineers who write business cases.
Key takeaway
Memorise the scale: North American greenfield facilities cost roughly $9-23 million per MW in 2026 before IT, and electricity is usually the biggest running cost.
Going deeper
- Cost-per-MW figures vary hugely with location, redundancy, density and scope, so always check whether a number includes land, grid connection, fit-out and IT equipment.
- Cushman & Wakefield found per-MW construction costs rose about 21% between late 2024 and its August 2026 guide, driven by equipment prices, labour wages and supply constraints.
- For AI deployments the IT bill dominates: industry estimates put total spending for a gigawatt of AI capacity in the tens of billions of dollars, mostly accelerators and networking.
- Lenders size loans using tenant credit, lease length and debt-service coverage; an investment-grade 15-year lease supports far more debt than short retail contracts.
- Depreciation choices move reported profits by billions: a longer server life lowers yearly depreciation, which is why analysts debate how long AI GPUs stay economically useful.
- Hidden costs include grid-connection contributions, rising insurance premiums, property-tax changes when incentives end and early refits when rack densities outgrow a building.
Common mistakes & misconceptions
- Comparing cost-per-MW figures without checking scope; one may exclude land, grid works, fit-out or IT entirely.
- Leaving electricity out of TCO; over ten years the power bill for a busy site can rival or exceed the cost of the building.
- Assuming long leases remove all risk; tenant concentration, delays and rate rises can still sink an overleveraged developer.
Try it: Ten-year TCO of 1 MW of IT load (Python, illustrative numbers)
mw, years = 1.0, 10
capex_per_mw = 13_000_000        # facility build, USD (illustrative)
pue, price_kwh = 1.3, 0.08       # efficiency and USD per kWh
staff_maint_per_year = 400_000   # illustrative

energy_kwh = mw * 1000 * 8760 * pue          # per year
energy_cost = energy_kwh * price_kwh
tco = capex_per_mw * mw + years * (energy_cost + staff_maint_per_year)
print(f"Yearly energy: {energy_kwh/1e6:.1f} GWh = ${energy_cost:,.0f}")
print(f"10-year TCO (no IT, no financing): ${tco:,.0f}")
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Capital cost per MW Cushman & Wakefield 2026 Data Center Development Cost Guide · Metric · Current · Business |
Facility build cost divided by IT capacity; 2026 North American greenfield costs ranged about $8.9-23.3 million per MW, excluding IT. | A 40 MW building at $13 million per MW needs roughly $520 million before any servers arrive. |
| Build cost breakdown Cost consultants and quantity surveyors · Concept · Current · Business |
Shares of capital cost by category; power infrastructure is the largest single block, ahead of shell, sitework and contingency. | Cushman & Wakefield's 2026 guide put power infrastructure at 21%, core, shell and sitework 17%, contingency 16% and land 7%. |
| IT capex vs facility capex Hyperscaler filings; industry analysts · Concept · Current · Business |
For AI campuses, GPUs, servers and networking usually cost several times more than the building, power and cooling around them. | An AI lab's board sees that the liquid-cooled hall is the smaller line; the accelerators inside dominate the budget. |
| Operating expenditure (OPEX) Operator accounts · Concept · Current · Business |
Running costs: electricity, staff, maintenance contracts, insurance, property taxes, water, security and connectivity; electricity usually dominates. | A 10 MW colocation site's yearly costs show power far ahead of payroll, maintenance and property taxes. |
| Energy cost per MW-year Calculation: MW × 8,760 h × PUE × price · Metric · Current · Business |
One MW of IT running all year at PUE 1.3 uses about 11.4 GWh; at $0.08 per kWh that costs roughly $0.9 million. | Moving to a site with power at $0.05 per kWh saves about $340,000 per MW each year. |
| Total cost of ownership (TCO) Finance and engineering practice · Metric · Current · Business |
All costs of owning and running an asset over its life, used to compare options such as build, lease or cloud. | A liquid-cooled design costs more upfront but wins on ten-year TCO thanks to lower PUE and higher density. |
| Build vs lease vs cloud Enterprise and hyperscaler decision practice · Concept · Current · Business |
Choosing between owning a facility, renting colocation or using public cloud, trading control and long-run cost against speed and flexibility. | A retailer moves steady workloads to colocation and keeps seasonal peaks in the cloud after a TCO study. |
| Depreciation and useful life Accounting standards; company filings · Concept · Current · Business |
Spreading an asset's cost over its expected life: buildings over decades, servers over about five to six years at large cloud firms. | In 2025 Meta lengthened many servers' lives to 5.5 years, while Amazon cut some from six to five years, citing AI's pace. |
| Triple-net (NNN) lease Real-estate lease structure · Concept · Current · Business |
Lease where the tenant pays rent plus operating costs such as power, taxes, insurance and maintenance; common for wholesale data centres. | A hyperscaler on an NNN lease pays its own electricity and a share of property tax on top of rent. |
| All-in colocation pricing Retail colocation contracts · Concept · Current · Business |
Retail contracts that bundle space, cooling and a power allowance into one monthly fee, or add metered power as a separate charge. | A small firm pays one monthly fee per cabinet covering space, cooling and up to 6 kW of power. |
| Construction loan Banks and private-credit lenders · Service · Current · Business |
Short-term loan funding a build in stages as work progresses, usually repaid by long-term debt once tenants occupy the building. | Lenders release funds monthly after an independent monitor certifies the work completed. |
| Data-centre securitisation (ABS and CMBS) Bond markets and rating agencies · Concept · Current · Business |
Bundling rents from leased data centres into rated bonds sold to investors, often cheaper long-term debt than bank loans. | A developer issues asset-backed notes secured on five fully leased buildings and uses the cash to build more. |
| Joint ventures and off-balance-sheet financing e.g. Meta and Blue Owl (Hyperion, 2025); Equinix xScale · Concept · Current · Business |
Investors own the buildings in a joint venture while the user leases them, sharing cost and keeping large debts off the user's balance sheet. | In Meta's Hyperion deal, a venture majority-owned by Blue Owl funds the Louisiana campus and Meta signs as tenant. |
| Cap rate and valuation Real-estate investors · Metric · Current · Business |
Capitalisation rate: yearly net operating income divided by property value; lower cap rates mean buyers pay more per dollar of rent. | A stabilised campus earning $60m a year sells at a 6% cap rate, valuing it at $1bn. |
| Cost of capital Corporate finance · Concept · Current · Business |
Blended return demanded by lenders and shareholders; higher interest rates raise it and can make marginal projects unviable. | When rates rise two points, Harbourline delays one building because its expected yield no longer beats its cost of capital. |
8.3 Hyperscalers: The Biggest Builders
Hyperscalers are the handful of giant cloud and internet companies that run millions of servers and build data centres at enormous scale. They both build their own campuses and lease huge amounts of capacity from landlords. Since the AI boom, their yearly spending on buildings, power and chips has grown to hundreds of billions of dollars.
Two kinds of hyperscaler
| Sell public cloud | Build mainly for own services | |
|---|---|---|
| Examples | AWS, Azure, Google Cloud, OCI, Alibaba | Meta, ByteDance, Apple |
| Revenue from | Renting compute and services | Ads, apps, devices, subscriptions |
| Custom chips | Trainium, Maia, TPU | MTIA, Apple silicon |
| Capacity mix | Self-build, leases, neoclouds | Self-build plus leases |
| Who you meet | Cloud customers and partners | Internal product teams |
Both build at enormous scale, but only cloud sellers rent capacity to the public.
Think of it like…
Hyperscalers are like the biggest supermarket chains: they own giant warehouses, also rent space from others, and their buying decisions shape the whole supply chain.
Real-world example
Fictional cloud firm Nimbus Corp plans a new AI region. It self-builds two 150 MW buildings on land it owns and leases another 100 MW from a developer to get capacity sooner. It orders transformers and chillers 30 months ahead and signs a long-term power deal for a new wind farm. Local colleges start training technicians because the campus will need about 300 staff.
How it works
- Forecast demand for cloud and AI services years ahead.
- Choose regions based on power, fibre, land, tax, water and customers.
- Mix self-build campuses with leased wholesale capacity and neocloud contracts.
- Standardise designs so the same building can be copied quickly around the world.
- Report capital expenditure (capex) to investors every quarter, which the whole industry watches.
Who uses it
Thousands of engineers, technicians, construction managers and suppliers work for or with hyperscalers; many entry-level technician jobs are at their campuses.
Key takeaway
Know the difference between hyperscalers that sell cloud (AWS, Azure, Google Cloud, Oracle, Alibaba) and those building mainly for their own apps (Meta, ByteDance, Apple).
Going deeper
- Hyperscale campuses typically range from 100 MW to well over 1 GW, built from repeated standard building designs so equipment orders, construction and commissioning can be copied worldwide.
- Hyperscalers mix self-build, wholesale leases and neocloud contracts: leasing buys speed, while self-build buys control and lower long-run cost.
- Quarterly capex guidance is the industry's most-watched demand signal; suppliers of transformers, generators, chillers and GPUs move with these numbers.
- Custom silicon such as TPU, Trainium, Maia and MTIA reduces dependence on one GPU vendor and lets operators design racks, power and cooling around their own chips.
- Cloud architecture uses regions made of availability zones, each with independent power and cooling, so a hyperscaler's physical design follows its software resilience model.
Common mistakes & misconceptions
- Calling every large data-centre owner a hyperscaler; the term means companies operating at massive cloud or internet scale.
- Assuming hyperscalers own all their capacity; they lease large amounts from developers and neoclouds.
- Treating announced capex as already-built capacity; projects take years and can be delayed or cancelled.
Try it: Rough sizing: how many GPUs fit in a given IT load (illustrative assumptions)
# Python: rough GPU count for a site (all inputs are assumptions)
it_load_mw = 150            # critical IT load
kw_per_gpu_all_in = 1.8     # GPU + CPU, network, storage share (assumed)
pue = 1.25

gpus = it_load_mw * 1000 / kw_per_gpu_all_in
grid_mw = it_load_mw * pue
print(f'~{gpus:,.0f} GPUs, needing ~{grid_mw:.0f} MW from the grid')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Hyperscaler capex Company earnings reports · Metric · Current · Business |
The four biggest US tech firms spent roughly $410bn on capex in 2025; after July 2026 earnings their combined 2026 guidance exceeded $700bn. | When Alphabet lifted its 2026 guidance to $195-205bn in July, suppliers of transformers, chillers and leased megawatts saw it as a demand signal. |
| Amazon Web Services (AWS) Amazon (NASDAQ: AMZN) · Company · Current · Business |
The largest public cloud by market share, running regions worldwide and designing its own Graviton and Trainium chips. | Project Rainier, an AWS cluster of nearly half a million Trainium2 chips in Indiana, was built for a leading AI lab and went live in 2025. |
| Microsoft Azure Microsoft (NASDAQ: MSFT) · Company · Current · Business |
Microsoft's cloud, a major AI compute provider that self-builds and also rents heavily from neoclouds and landlords. | Its Fairwater AI datacentre in Mount Pleasant, Wisconsin uses GB200 racks and a closed-loop liquid cooling plant; a second Fairwater site is in Atlanta. |
| Google Cloud Alphabet (NASDAQ: GOOGL) · Company · Current · Business |
Google's cloud and internal infrastructure, known for custom TPU AI chips and early liquid cooling at scale. | Google trains its Gemini models on TPU pods housed in its own liquid-cooled data centres. |
| Meta Meta Platforms (NASDAQ: META) · Company · Current · Business |
Builds huge campuses for Facebook, Instagram and its AI models; does not sell public cloud. | Its 1 GW Prometheus cluster in New Albany, Ohio began coming online in phases during 2026 as its first gigawatt-class AI site. |
| Meta Hyperion Meta; Blue Owl joint venture; Entergy Louisiana · Facility · Emerging · Business |
Planned AI campus in Richland Parish, Louisiana designed to scale up to about 5 GW, powered partly by new gas plants. | Financed through a joint venture with Blue Owl Capital announced in October 2025, with Meta as tenant. |
| Oracle Cloud Infrastructure (OCI) Oracle (NYSE: ORCL) · Company · Current · Business |
Oracle's cloud, which grew into a major AI capacity provider through huge contracts with OpenAI and others. | In July 2025 Oracle and OpenAI agreed to develop about 4.5 GW of extra US Stargate capacity. |
| Alibaba Cloud Alibaba Group (NYSE: BABA; HKEX: 9988) · Company · Current · Business |
China's largest cloud provider, also operating regions across Asia, the Middle East and Europe. | In early 2025 Alibaba announced plans to spend over RMB 380bn on cloud and AI infrastructure over three years. |
| Tencent Cloud Tencent Holdings (HKEX: 0700) · Company · Current · Business |
Cloud arm of the company behind WeChat and major games, running data centres in China and abroad. | A game publisher hosts its Asian servers in Tencent Cloud regions close to players. |
| ByteDance ByteDance (private) · Company · Current · Business |
Owner of TikTok and Douyin, a top buyer of data-centre capacity in Asia, often leasing from third-party operators. | Large leased campuses in South-East Asia host ByteDance services and AI workloads. |
| Apple Apple (NASDAQ: AAPL) · Company · Current · Business |
Runs its own data centres for iCloud and Siri and uses Apple-silicon servers for its Private Cloud Compute AI service. | In 2025 Apple announced a Houston factory to build servers for its AI data centres. |
| Custom AI silicon Google TPU, AWS Trainium, Microsoft Maia, Meta MTIA · Technology · Current · IT |
Chips designed by hyperscalers themselves to run AI more cheaply than general-purpose GPUs. | A cloud runs its own AI assistant on in-house accelerators while renting NVIDIA GPUs to customers. |
8.4 Colocation & Wholesale Leaders
Colocation companies build data centres and rent space, power and connectivity to many customers. Some focus on small 'retail' customers and rich interconnection; others build whole buildings for single big tenants (wholesale). Most of the largest are listed REITs or owned by private-equity and infrastructure investors.
Retail vs wholesale colocation
| Retail colocation | Wholesale / hyperscale | |
|---|---|---|
| Typical deal | Racks, cages, suites | Whole halls or buildings |
| Size | A few kW to a few MW | Tens to hundreds of MW |
| Contract | Often 1-5 years | Often 10-20 years |
| Price per kW | Higher | Lower |
| Key value | Interconnection density | Speed, scale, cost |
| Examples | Equinix, NTT, Global Switch | QTS, Vantage, Aligned, AirTrunk |
Same industry, very different contracts, buildings and customers.
Think of it like…
Retail colocation is like a serviced office block where many firms rent desks; wholesale is like a developer building a whole office tower for one big company.
Real-world example
Fictional fintech Ledgerly needs low-latency links to banks and clouds, so it rents four racks in a carrier-neutral retail facility with 300 networks on site. Meanwhile, fictional AI company Quanta Labs signs a 40 MW build-to-suit lease with a wholesale developer for a new campus. Both are colocation customers, but their contracts, prices and buildings look completely different.
How it works
- Retail providers sell racks and cages with many interconnection options in city-centre hubs.
- Wholesale developers build large halls or campuses for one or a few hyperscale tenants.
- Ownership is often REITs (listed) or private-equity and infrastructure funds (private).
- Platforms change hands frequently, so always check the latest owner before quoting it.
Who uses it
Colocation providers employ many critical facilities engineers, technicians, sales engineers and customer-success staff, making them a common first employer.
Key takeaway
Equinix and Digital Realty are the two big listed data-centre REITs; most other big operators are privately owned by investment funds.
Going deeper
- Ownership churns quickly: since 2021 private-equity and infrastructure investors have bought CyrusOne, QTS, Switch, AirTrunk and Aligned, so always check the latest owner and deal status.
- Listed REITs such as Equinix, Digital Realty and Iron Mountain publish detailed quarterly reports on bookings, pricing, churn and capacity under construction, which make free training material.
- Retail operators win on ecosystems: networks, clouds and internet exchanges inside one building make each new customer more valuable to the others.
- Wholesale developers compete on power availability, delivery speed, land banks and the ability to finance gigawatt-scale campuses pre-leased to a few tenants.
- Regional specialists such as Princeton Digital Group, Scala, Data4 and AirTrunk are major local employers; global brand names are only part of the jobs map.
Common mistakes & misconceptions
- Quoting company ownership from old articles; mergers and sales change owners frequently.
- Assuming 'colocation' always means small racks; wholesale colocation leases entire buildings.
- Comparing operators by number of sites alone; megawatts and interconnection reach matter more.
Try it: Compare retail vs wholesale deals for the same 1 MW (illustrative)
# Python: same power, different deal styles (made-up prices)
deals = {
  'Retail (200 racks x 5 kW)': {'kw': 1000, 'usd_kw_month': 250, 'xconnects': 40, 'xc_fee': 300},
  'Wholesale (1 MW suite)':    {'kw': 1000, 'usd_kw_month': 150, 'xconnects': 4,  'xc_fee': 300},
}
for name, d in deals.items():
    monthly = d['kw'] * d['usd_kw_month'] + d['xconnects'] * d['xc_fee']
    print(f'{name:28s} ${monthly:,.0f} per month')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Equinix Equinix Inc. (NASDAQ: EQIX), REIT · Company · Current · Business |
Largest retail colocation and interconnection provider, with about 260 data centres in over 30 countries. | Its xScale joint ventures, with partners including GIC and CPP Investments, build hyperscale capacity alongside its retail sites. |
| Digital Realty Digital Realty Trust (NYSE: DLR), REIT · Company · Current · Business |
Global data-centre REIT offering wholesale and colocation through its PlatformDIGITAL offering, with 300+ facilities. | It bought European operator Interxion (announced 2019) and a majority stake in Africa's Teraco in 2022. |
| NTT DATA Global Data Centers NTT DATA, part of Japan's NTT group · Company · Current · Business |
One of the world's largest data-centre operators, with campuses across Japan, the US, Europe, India and Asia. | In 2025 NTT listed a data-centre REIT in Singapore holding some of its stabilised facilities. |
| CyrusOne Owned by KKR and Global Infrastructure Partners (now part of BlackRock) · Company · Current · Business |
US-born wholesale and hyperscale developer, taken private in March 2022 for about $15bn. | It builds large leased campuses for cloud tenants in the US, Europe and Japan. |
| QTS Data Centers Blackstone (acquired 2021, about $10bn) · Company · Current · Business |
Fast-growing US hyperscale and wholesale developer owned by Blackstone funds. | QTS builds multi-hundred-megawatt campuses for hyperscalers in markets such as Atlanta and Virginia. |
| Vantage Data Centers Backed by DigitalBridge and co-investors · Company · Current · Business |
Hyperscale campus developer across North America, EMEA and Asia-Pacific. | Its Frontier campus in Shackelford County, Texas was named among the Stargate sites in 2025. |
| STACK Infrastructure Blue Owl Capital (via its 2025 purchase of IPI Partners) · Company · Current · Business |
Wholesale and hyperscale developer; its European colocation arm was sold to Apollo in 2025 and other regions have been in sale talks. | STACK builds powered campuses pre-leased to cloud providers. |
| Aligned Data Centers AI Infrastructure Partnership, MGX and BlackRock's GIP · Company · Current · Business |
Dallas-based hyperscale developer bought from Macquarie for about $40bn, a deal completed in 2026, the largest data-centre deal so far. | Aligned runs dozens of campuses across the US and Latin America for cloud and AI tenants. |
| Switch Taken private by DigitalBridge and IFM Investors in 2022 (about $11bn) · Company · Current · Business |
US operator of very large, highly secure campuses in Nevada, Arizona, Georgia and Michigan. | Its Las Vegas and Reno campuses are known for proprietary cooling and security designs. |
| AirTrunk Blackstone with CPP Investments (acquired 2024, about A$24bn) · Company · Current · Business |
Hyperscale operator founded in Australia, expanding across Asia-Pacific including Singapore, Japan, Malaysia, Hong Kong and India. | AirTrunk builds large campuses leased mainly to cloud and AI tenants in Sydney, Melbourne and Johor. |
| Iron Mountain Data Centers Iron Mountain (NYSE: IRM), REIT · Company · Current · Business |
Data-centre arm of the records-storage company, growing fast in leased hyperscale and colocation capacity. | A government agency moves from paper archives with Iron Mountain to racks in its data centres. |
| Princeton Digital Group (PDG) Backed by Warburg Pincus · Company · Current · Business |
Singapore-headquartered operator in Asia-Pacific markets including Singapore, Indonesia, India, Japan and China. | A cloud provider leases PDG capacity in Jakarta to serve Indonesian users locally. |
| Global Switch Majority-owned by Jiangsu Shagang Group · Company · Current · Business |
Large carrier-neutral operator in London, Amsterdam, Frankfurt, Paris, Singapore and Hong Kong; sold its Australian business in 2025. | Shareholders have explored selling the business since 2022 — check the latest owner before citing it. |
| EdgeConneX EQT Infrastructure · Company · Current · Business |
Builds edge and hyperscale data centres globally, often build-to-suit for a single customer. | A content network leases a small EdgeConneX site near a city to cut video latency. |
| Data4 Brookfield · Company · Current · Business |
European operator with large campuses in France, Italy, Spain, Germany and other markets. | A hyperscaler leases a Data4 hall near Paris for its French cloud region. |
| Scala Data Centers DigitalBridge · Company · Current · Business |
A leading hyperscale-focused operator in Latin America, headquartered in Brazil. | Scala builds large campuses near São Paulo powered mainly by renewable energy contracts. |
8.5 AI Cloud Builders (Neoclouds) & Giant AI Campuses
Since 2023, demand for AI has created a new kind of company, the 'neocloud', that rents out huge numbers of GPUs. At the same time, AI labs and cloud giants announced campuses measured in gigawatts, far bigger than traditional data centres. Many of these projects are partnerships between chip makers, cloud providers, investors and energy companies.
Think of it like…
Neoclouds are like equipment-hire firms that bought thousands of rare power tools early and rent them by the hour or year to builders who cannot get their own.
Real-world example
Fictional AI lab Corvid signs a three-year contract with fictional neocloud Kestrel Compute for 16,000 GPUs. Kestrel does not own a building, so it leases a 40 MW liquid-cooled hall from a developer and borrows against Corvid's contract to buy the servers. If Corvid's demand falls, Kestrel still owes rent and loan payments, which is why investors watch neocloud contracts closely.
How it works
- An AI customer commits to a multi-year capacity contract.
- The neocloud uses that contract to raise debt and buy GPUs, networking and storage.
- It leases or builds liquid-cooled, high-density halls with fast power delivery.
- Clusters are installed, burned in and handed over; the customer pays per GPU-hour or per month.
- Gigawatt campuses repeat this at enormous scale, often with on-site or dedicated power.
Who uses it
AI infrastructure engineers, HPC technicians, electrical and mechanical engineers, and finance teams are heavily recruited by neoclouds and AI campus builders.
Key takeaway
Announced gigawatts are not the same as operating gigawatts: always ask whether a project is announced, under construction or energised.
Going deeper
- Neocloud economics depend on utilisation and contract length: GPUs lose value quickly as new generations arrive, so lenders prefer long take-or-pay contracts with creditworthy customers.
- Customer concentration is a key risk: a few AI labs or hyperscalers often provide most revenue, so one contract change can reshape a company's outlook.
- Many neoclouds lease from developers or convert former crypto-mining sites, because those sites already have grid connections and electrical infrastructure.
- Gigawatt AI campuses combine many buildings, on-site substations and sometimes on-site generation; they are delivered in phases, so energised capacity lags announced capacity by years.
- Partnership structures are complex: chip makers invest in customers, customers invest in suppliers and clouds rent from neoclouds, so read filings to see who carries the financial risk.
Common mistakes & misconceptions
- Treating announced gigawatts as operating capacity; check the phase, energisation date and power source.
- Assuming neoclouds own their buildings; many lease halls from developers or former crypto miners.
- Quoting fast-moving deal values without dates; AI contracts are frequently revised, expanded or cancelled.
Try it: Simple GPU-rental economics (illustrative numbers only)
# Python: monthly revenue and power for a rented GPU cluster
gpus = 16_000
price_per_gpu_hour = 2.20     # assumed contract price, USD
hours = 730                   # hours in an average month
kw_per_gpu_all_in = 1.8       # assumed IT power per GPU incl. network

revenue = gpus * price_per_gpu_hour * hours
it_mw = gpus * kw_per_gpu_all_in / 1000
print(f'Revenue ~ ${revenue/1e6:.1f}m per month for ~{it_mw:.0f} MW of IT load')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| CoreWeave CoreWeave Inc. (NASDAQ: CRWV) · Company · Current · Business |
Largest pure-play GPU cloud; listed in March 2025. Microsoft was its biggest customer in 2024, with large OpenAI and Meta contracts since. | Its $9bn all-stock deal to buy landlord Core Scientific was rejected by Core Scientific shareholders in October 2025. |
| Crusoe Crusoe (private) · Company · Emerging · Business |
AI infrastructure builder that began by using otherwise-flared gas for computing, now developing large AI campuses. | Crusoe developed the Abilene, Texas campus, with Lancium, that Oracle runs for OpenAI's Stargate. |
| Lambda Lambda (private) · Company · Emerging · Business |
GPU cloud and AI-cluster provider popular with researchers and AI startups. | In late 2025 Lambda signed a multibillion-dollar deal to supply GPU infrastructure to Microsoft. |
| Nebius Nebius Group (NASDAQ: NBIS), Amsterdam · Company · Emerging · Business |
AI cloud formed from Yandex's former international business, with data centres in Finland, the US and Europe. | In September 2025 it agreed a multi-year deal worth about $17.4bn to supply Microsoft from a new site in Vineland, New Jersey. |
| Nscale Nscale (private), London · Company · Emerging · Business |
UK-founded AI cloud (2024) building GPU sites in Europe and the US; partner in OpenAI's Stargate Norway and UK plans. | Nscale agreed to supply Microsoft with capacity using around 200,000 NVIDIA GPUs across several sites. |
| Fluidstack Fluidstack (private), London · Company · Emerging · Business |
AI cloud provider that builds and operates large GPU clusters for AI labs and governments. | In November 2025 a leading AI lab announced a $50bn plan with Fluidstack to build data centres in Texas and New York. |
| Together AI Together AI (private) · Company · Emerging · IT |
AI cloud focused on running and fine-tuning open-source models, operating its own GPU clusters. | A startup fine-tunes an open model on Together AI instead of buying its own servers. |
| Core Scientific Core Scientific (NASDAQ: CORZ) · Company · Emerging · Business |
Former bitcoin miner converting its powered sites into high-density AI hosting, with CoreWeave as a major tenant. | Shows a common pattern: crypto-mining sites with grid connections being repurposed for AI. |
| Stargate OpenAI, SoftBank, Oracle, MGX (announced 21 January 2025) · Concept · Emerging · Business |
OpenAI-led joint venture announced in January 2025 with SoftBank, Oracle and MGX as initial equity backers, targeting up to $500bn of US AI infrastructure. | It became an umbrella brand for OpenAI's data-centre plans; in April 2026 OpenAI said it had contracted about 10 GW of compute, years ahead of target. |
| Stargate Abilene Crusoe / Lancium site, operated by Oracle for OpenAI · Facility · Emerging · Business |
The first Stargate campus in Abilene, Texas, built by Crusoe with liquid-cooled NVIDIA GB200 racks and planned to reach about 1.2 GW. | Other announced US sites include Shackelford and Milam counties (Texas), Doña Ana County (New Mexico) and Lordstown (Ohio). |
| Stargate UAE G42 (built by Khazna) with OpenAI, Oracle, NVIDIA, Cisco, SoftBank · Facility · Emerging · Business |
A 1 GW AI cluster in Abu Dhabi announced in May 2025, with its first 200 MW phase scheduled for completion in 2026. | Part of a larger UAE-US AI campus plan in Abu Dhabi. |
| xAI Colossus xAI, Memphis, Tennessee · Facility · Emerging · Business |
Memphis AI supercomputer: the first ~100,000-GPU phase was built in about 122 days in 2024, and Colossus 2 approached 1 GW in 2026. | Its use of gas turbines for power drew air-quality complaints and legal challenges from local groups. |
| OpenAI chip-supply deals OpenAI with NVIDIA, AMD and Broadcom (2025) · Concept · Emerging · Business |
Multi-gigawatt agreements: NVIDIA up to 10 GW (letter of intent), AMD 6 GW of Instinct GPUs, Broadcom 10 GW of custom chips. | AMD's deal starts with 1 GW of MI450 GPUs planned from the second half of 2026; check latest status of each. |
| GPU-backed debt financing Neoclouds with private-credit lenders and banks · Concept · Emerging · Business |
Loans secured on GPU servers and customer contracts, letting neoclouds buy hardware quickly but adding risk if GPU values or demand fall. | A neocloud borrows against a multi-year AI-lab contract and the GPUs themselves, repaying the loan from monthly rental income. |
8.6 The World's Major Data Centre Markets
Data centres cluster in certain places, called markets, where power, fibre networks, land and customers come together. A few hubs such as Northern Virginia, Frankfurt and Singapore are famous, while new AI campuses are moving to wherever large amounts of power are available. Knowing the markets helps you understand where the jobs are.
Think of it like…
Markets are like airport hubs: once many airlines (networks) meet in one place, everyone else wants to be there too, until the runways (power) run out.
Real-world example
Fictional operator Northlight wants to build 100 MW. Its first choice, a famous city hub, has a five-year wait for grid power and strict planning rules. It instead picks a secondary market 300 km away where a utility can deliver power in two years and fibre routes already pass by. Latency-sensitive customers stay in the hub, while AI training moves to the new site.
How it works
- Primary markets grew where internet exchanges and carriers met.
- Cloud regions followed, making those hubs even bigger.
- Power and land shortages pushed growth to secondary markets and new regions.
- AI training, which needs less low latency, moves to wherever gigawatts can be found.
- Governments now shape markets with grid rules, tax incentives, moratoriums and data-sovereignty laws.
Who uses it
Site selection teams, developers, brokers and job seekers all track markets; technician jobs are concentrated in these hubs.
Key takeaway
Memorise FLAP-D (Frankfurt, London, Amsterdam, Paris, Dublin) for Europe and Northern Virginia as the world's largest market.
Going deeper
- Markets are compared by operational MW, MW under construction, pre-leasing, vacancy, rents and absorption; brokers such as CBRE, JLL and Cushman & Wakefield publish these figures regularly.
- Interconnection-rich hubs grew around internet exchanges: DE-CIX in Frankfurt, LINX in London, AMS-IX in Amsterdam and the carrier-dense campuses of Ashburn in Northern Virginia.
- AI training is less latency-sensitive than user-facing services, so it moves to power-rich areas such as West Texas, the Nordics and the Middle East, while inference stays nearer users.
- Data-sovereignty and localisation rules in India, the EU, the Gulf states and elsewhere push capacity into each country, creating local markets regardless of power prices.
- Constraints shift growth quickly: grid limits, moratoria, tax-incentive changes and water rules can move demand to neighbouring regions within a few years, as Singapore's limits did for Johor.
Common mistakes & misconceptions
- Assuming all growth stays in famous hubs; power scarcity is pushing builds to secondary and rural markets.
- Ignoring latency: AI training can go remote, but trading, gaming and interconnection still need city hubs.
- Quoting old market rankings; capacity league tables shift every year.
Try it: Rank markets by available power (ILLUSTRATIVE, made-up numbers — not real data)
# market_snapshot.csv  (fictional values for practice only)
market,operating_mw,under_construction_mw,vacancy_pct,years_to_new_power
Hub City A,4200,1800,1.2,5
Secondary B,900,1100,3.5,2
Remote Campus C,150,1500,0.0,1

# Python: load and sort by power deliverable soonest
import csv
rows = list(csv.DictReader(open('market_snapshot.csv')))
for r in sorted(rows, key=lambda r: int(r['years_to_new_power'])):
    print(r['market'], r['years_to_new_power'], 'years to new power')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Northern Virginia Loudoun, Prince William & Fairfax counties; Dominion Energy · Market · Current · Business |
The world's largest data-centre market by operating capacity, measured in gigawatts, with very low vacancy and a dense cloud, colocation and fibre ecosystem. | Developers pay premium land prices in Loudoun and Prince William counties, then wait years for Dominion Energy transmission upgrades. |
| Dallas-Fort Worth Texas; ERCOT grid · Market · Current · Business |
One of the largest and fastest-growing US markets, with cheap land and Texas's independent grid. | Texas Senate Bill 6 (2025) set new rules for very large loads connecting to the grid. |
| Phoenix Arizona; APS and SRP utilities · Market · Current · Business |
Major hyperscale hub in the desert, attractive for land and low natural-disaster risk but scrutinised over water. | New campuses there favour closed-loop or air-cooled designs to cut water use. |
| Atlanta Georgia; Georgia Power · Market · Current · Business |
Grew into one of the top US markets in the 2020s on the back of hyperscale and AI campuses. | Microsoft's second Fairwater AI site is in the Atlanta area. |
| Chicago Illinois; ComEd · Market · Current · Business |
The Midwest's main hub, with dense fibre and many colocation sites around Elk Grove Village. | A trading firm colocates near Chicago's futures exchange data centres for low latency. |
| Silicon Valley Santa Clara and San Jose, California · Market · Current · Business |
Historic hub with high prices and tight power, mainly serving tech companies and interconnection. | Operators there wait years for new utility capacity, so space is scarce and expensive. |
| Columbus & central Ohio Ohio; AEP Ohio · Market · Emerging · Business |
Fast-growing hyperscale market with AWS, Google and Meta campuses; regulators approved a special data-centre tariff in 2025. | Meta's Prometheus AI cluster is in New Albany, near Columbus. |
| West & Central Texas Abilene and other rural Texas counties · Market · Emerging · Business |
New AI-campus frontier with abundant land, wind, solar and gas. | The first Stargate campus in Abilene grew from open land to large AI buildings within about a year. |
| FLAP-D Frankfurt, London, Amsterdam, Paris, Dublin · Market · Current · Business |
Europe's five traditional primary markets, built around big internet exchanges such as DE-CIX, LINX and AMS-IX. | Grid limits in Dublin and Amsterdam restrict new builds, pushing growth to the edges and other countries. |
| Nordics & emerging Europe Norway, Sweden, Finland, Denmark; plus Madrid, Milan, Warsaw · Market · Emerging · Business |
Cool climate and renewable hydro power attract AI and HPC; southern and eastern cities are growing fast. | OpenAI and partners announced a Stargate Norway site near Narvik in 2025. |
| Singapore Singapore government (IMDA, EDB) · Market · Current · Business |
Asia's key interconnection hub; a 2019 pause on new builds was replaced by selective, efficiency-focused allocation. | New capacity is awarded only to highly efficient, greener designs, so growth spills into Malaysia. |
| Johor Malaysia · Market · Emerging · Business |
Across the causeway from Singapore, one of the fastest-growing markets in the world in the mid-2020s. | Hyperscalers and Chinese tech firms lease large campuses in Johor to serve the region. |
| Mature APAC hubs Tokyo, Osaka, Seoul, Sydney, Melbourne, Hong Kong · Market · Current · Business |
Established cloud and enterprise markets with strong demand and high land and power costs. | A game company keeps servers in Tokyo and Seoul to give local players low latency. |
| India Mumbai (Navi Mumbai), Chennai, Hyderabad · Market · Emerging · Business |
Rapidly growing market driven by cloud, data-localisation rules and submarine cable landings in Mumbai and Chennai. | A payments firm keeps all Indian customer data in Mumbai data centres to meet local rules. |
| Middle East UAE (Abu Dhabi, Dubai), Saudi Arabia · Market · Emerging · Business |
Sovereign-funded AI build-out with cheap energy, including Stargate UAE and Saudi Arabia's HUMAIN. | Gulf states pitch abundant power and capital to attract AI compute from US firms. |
| Latin America Querétaro (Mexico), São Paulo (Brazil), Santiago (Chile) · Market · Emerging · Business |
The region's main hubs, growing as clouds open local regions near large populations. | A streaming firm serves Brazil from São Paulo instead of Miami to cut buffering. |
8.7 Power Equipment Vendors
A handful of global companies make most of the electrical equipment inside data centres: UPS systems, switchgear, transformers, power distribution and backup generators. Because AI campuses need so much of this kit, these vendors' factories, lead times and new products shape how fast the industry can grow. You will see their logos on almost every panel you work on.
Think of it like…
These vendors are like the few big car makers: every road (data centre) is full of their products, and when their factories are busy, everyone waits.
Real-world example
Fictional developer Brightfield orders equipment for a 60 MW building. It buys medium-voltage switchgear and transformers from one supplier, UPS from another, and twenty 3 MW diesel generators from a third. The transformers have the longest wait, so they are ordered 24 months before handover. Technicians later attend each vendor's training so they can operate and maintain the kit safely.
How it works
- Designers specify equipment by rating, redundancy and standards compliance.
- Procurement compares vendors on price, lead time, efficiency and local service support.
- Factory acceptance tests (FAT) are witnessed before shipping.
- Vendor field engineers support installation, commissioning and maintenance contracts.
- Site teams receive vendor training and spare-parts kits.
Who uses it
Electrical engineers, critical facilities technicians, commissioning agents and procurement teams deal with these vendors daily; many also hire field service engineers.
Key takeaway
Learn at least one UPS family and one generator make in depth; interviewers love it when you can describe a real unit's modes and alarms.
Going deeper
- Long-lead items are the bottleneck: large power transformers, MV switchgear, generators and gas turbines have faced waits of many months to years, so developers reserve factory slots early.
- Vendors increasingly sell integrated prefabricated power modules, e-houses and skids, shifting work from the construction site to factories and witnessed factory acceptance tests.
- Service networks matter as much as hardware: response times, local spare stock and trained field engineers often decide which UPS or generator brand wins a tender.
- AI power trends are reshaping product lines: 800 V DC and ±400 V DC distribution, solid-state transformers, battery-backup shelves and grid-interactive UPS all appear on vendor roadmaps.
- Interviewers value brand fluency: knowing a Liebert, Galaxy or Eaton 93-series UPS, or a Cummins or Caterpillar generator controller, signals hands-on readiness.
Common mistakes & misconceptions
- Confusing Siemens AG with Siemens Energy, or GE Vernova with GE Aerospace; they are separate listed companies.
- Ordering long-lead equipment late; lead times can exceed the whole construction period.
- Assuming all UPS units behave the same; operating modes, bypass logic and alarms differ by vendor and model.
Try it: Generator count for a building (worked N+1 example)
# Python: how many 3 MW gensets for 24 MW of facility load at N+1?
import math
load_mw = 24.0
gen_mw = 3.0          # rated output per genset (example)
derate = 0.9          # allow for altitude/temperature (assumed)
n = math.ceil(load_mw / (gen_mw * derate))
print(f'N = {n}, N+1 = {n+1} generators')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Schneider Electric Schneider Electric (France) · Company · Current · Electrical |
Major supplier of UPS (Galaxy, APC), switchgear, PDUs and EcoStruxure monitoring software. | Moved into liquid cooling by buying a majority stake in Motivair, completed in 2025. |
| Vertiv Vertiv Holdings (NYSE: VRT), USA · Company · Current · Electrical |
Former Emerson business making Liebert UPS, power distribution and thermal management for data centres. | Bought CoolTera in 2023 to add CDUs and works with NVIDIA on AI reference designs. |
| Eaton Eaton (NYSE: ETN), Ireland-domiciled · Company · Current · Electrical |
Supplies UPS, switchgear, busway and power-management software. | Agreed in late 2025 to buy Boyd's thermal business, adding liquid cooling to its power portfolio. |
| ABB ABB (Switzerland/Sweden) · Company · Current · Electrical |
Makes medium- and low-voltage switchgear, UPS, transformers, drives and prefabricated power rooms. | A campus uses ABB medium-voltage switchgear at its main intake substation. |
| Siemens Siemens AG (Germany) · Company · Current · Electrical |
Supplies switchgear, protection relays and building-management systems; Siemens Energy, a separate company, makes turbines and large transformers. | A site's electrical monitoring and fire detection run on Siemens systems. |
| Legrand Legrand (France) · Company · Current · Electrical |
Rack PDUs (Raritan, Server Technology), Starline busway, cabinets and cable management. | Each rack gets two Legrand intelligent PDUs reporting power per outlet to DCIM. |
| Hitachi Energy Hitachi Energy (Hitachi group) · Company · Current · Electrical |
One of the biggest makers of power transformers, grid equipment and HVDC systems. | A utility orders Hitachi Energy transformers for a new substation feeding a data-centre campus. |
| GE Vernova GE Vernova (NYSE: GEV), spun off from GE in 2024 · Company · Current · Electrical |
Gas turbines, grid equipment and wind turbines; AI demand has filled its gas-turbine order book for years. | An AI campus orders aeroderivative gas turbines for on-site power while it waits for the grid. |
| Mitsubishi Electric Mitsubishi Electric (Japan) · Company · Current · Electrical |
Large three-phase UPS systems and electrical equipment used widely in North American data centres. | A colocation hall runs on modular Mitsubishi Electric UPS units in a 2N design. |
| Socomec Socomec (France) · Company · Current · Electrical |
European specialist in UPS, static transfer switches and power switching and monitoring. | A European operator uses Socomec STS units to feed single-corded network gear from two sources. |
| Delta Electronics Delta Electronics (Taiwan) · Company · Current · Electrical |
Power supplies, UPS and rack power shelves, including high-voltage DC systems for AI racks. | AI racks use rack-level power shelves converting AC to DC for dense GPU trays. |
| Cummins Cummins Inc. (NYSE: CMI), USA · Company · Current · Electrical |
Leading maker of large diesel generator sets and paralleling controls for backup power. | A site's twenty Cummins gensets are load-bank tested every year. |
| Caterpillar Caterpillar (NYSE: CAT), USA · Company · Current · Electrical |
Diesel and gas generator sets; its Solar Turbines unit makes gas turbines used for on-site power. | A campus mixes Cat diesel standby gensets with gas units for prime power. |
| Rolls-Royce Power Systems (mtu) Rolls-Royce plc, mtu brand (Germany) · Company · Current · Electrical |
Large mtu diesel generator sets widely used for data-centre standby power. | A European site meets its backup needs with mtu gensets running on HVO renewable diesel. |
| Rehlko Rehlko (formerly Kohler Energy, renamed 2024) · Company · Current · Electrical |
Maker of industrial generators and power systems, previously sold under the Kohler Energy name. | A technician's older site still has Kohler-branded gensets now supported by Rehlko. |
| Bloom Energy Bloom Energy (NYSE: BE), USA · Company · Emerging · Electrical |
Solid-oxide fuel cells that make electricity on site from natural gas or hydrogen. | AI campuses short of grid power add fuel cells as 'bridge' or permanent on-site generation. |
8.8 Cooling, Rack & Cabling Vendors
Another set of companies makes the cooling plant, racks and cables. HVAC giants supply chillers and air handlers, specialists build liquid-cooling systems for AI racks, and structured-cabling firms supply the copper and fibre that connect everything. The liquid-cooling market has seen many acquisitions as big firms race to offer AI-ready solutions.
Think of it like…
If the data centre were a human body, the cooling vendors make the heart and lungs, and the cabling vendors make the nerves.
Real-world example
Fictional neocloud Kestrel Compute fits out a 20 MW AI hall. It buys air-cooled chillers from an HVAC major, in-row CDUs from a liquid-cooling specialist and 4,000 km of fibre plus pre-terminated trunks from a cabling vendor. The cabling vendor's design team plans every cable route so the GPU cluster can be wired in weeks instead of months.
How it works
- Mechanical engineers size chillers, air handlers and liquid loops for the IT load.
- Liquid-cooling vendors provide CDUs, cold plates or immersion tanks matched to the servers.
- Rack and containment vendors supply cabinets, aisle containment and rack cooling.
- Cabling vendors provide copper, fibre, connectors and pathways, often pre-terminated.
- All are tested together during commissioning before the IT goes live.
Who uses it
Mechanical engineers, cooling technicians, structured-cabling installers and data-centre technicians use these products every day.
Key takeaway
Expect interview questions on why AI racks need liquid cooling; name a CDU and a cold-plate vendor and explain what each does.
Going deeper
- HVAC majors supply the plant (chillers, cooling towers, air handlers) while liquid-cooling specialists supply CDUs, manifolds and cold plates; AI halls need both working together.
- Consolidation is rapid: Schneider took a majority stake in Motivair, Vertiv bought CoolTera, Flex bought JetCool, Ecolab bought CoolIT and Eaton agreed to buy Boyd's thermal business.
- Server makers and GPU vendors publish reference designs listing qualified CDUs, cold plates and coolants, so warranty and compatibility strongly shape vendor choice.
- AI clusters need many times more fibre than traditional halls because every GPU connects to high-speed back-end networks, driving demand for high-fibre-count cables and pre-terminated trunks.
- Immersion cooling has its own specialist suppliers, but direct-to-chip cold plates have become the mainstream choice for current GPU rack designs.
Common mistakes & misconceptions
- Assuming one vendor supplies the whole cooling chain; chillers, CDUs and cold plates often come from different firms.
- Ignoring coolant and wetted-material compatibility when mixing CDU and cold-plate vendors.
- Quoting pre-acquisition company names in interviews; check current ownership first.
Try it: Simple weighted scoring matrix to compare cooling vendors (fictional scores)
# Python: weighted vendor scoring (fictional vendors and scores)
weights = {'lead_time': 0.3, 'efficiency': 0.3, 'service': 0.25, 'price': 0.15}
vendors = {
  'Vendor A': {'lead_time': 6, 'efficiency': 9, 'service': 8, 'price': 5},
  'Vendor B': {'lead_time': 9, 'efficiency': 7, 'service': 6, 'price': 8},
}
for v, s in vendors.items():
    print(v, round(sum(weights[k] * s[k] for k in weights), 2))
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Trane Technologies Trane Technologies (NYSE: TT) · Company · Current · Mechanical |
HVAC major making chillers, controls and cooling for data centres; strategic investor in LiquidStack. | A campus uses Trane air-cooled chillers with free-cooling coils. |
| Johnson Controls Johnson Controls (NYSE: JCI) · Company · Current · Mechanical |
YORK chillers, building automation, fire and security; bought Silent-Aire for custom data-centre air handling in 2021. | A hyperscaler buys prefabricated JCI cooling modules for a fast build. |
| Carrier Carrier Global (NYSE: CARR) · Company · Current · Mechanical |
Chillers, air handlers and controls with a growing data-centre product line. | A colocation operator uses Carrier chillers on its rooftop plant. |
| Daikin Applied Daikin Industries (Japan) · Company · Current · Mechanical |
Commercial chillers and air-handling equipment, including units designed for data centres. | A designer selects Daikin Applied chillers with high entering-water temperatures for efficiency. |
| STULZ STULZ GmbH (Germany, family-owned) · Company · Current · Mechanical |
Precision air conditioning (CRAC/CRAH), chillers and liquid-cooling CDUs. | An enterprise data hall runs STULZ CRAH units on its raised floor. |
| Munters Munters (Sweden) · Company · Current · Mechanical |
Indirect evaporative coolers and air-handling units that cut compressor energy. | A site in a dry climate uses Munters indirect evaporative units for most of the year. |
| Modine (Airedale) Modine Manufacturing (NYSE: MOD) · Company · Current · Mechanical |
Chillers, CRAH units and air handlers, sold in Europe under the Airedale by Modine brand. | A UK colocation site uses Airedale chillers and CRAHs. |
| CoolIT Systems Ecolab (acquisition completed July 2026) · Company · Current · Mechanical |
Canadian pioneer of direct-to-chip liquid cooling: cold plates and coolant distribution units (CDUs). | Server makers ship GPU servers fitted with CoolIT cold plates for liquid-cooled halls. |
| JetCool Flex (acquired 2024) · Company · Emerging · Mechanical |
Makes microconvective cold plates that jet coolant directly at chip hot spots. | A server maker tests JetCool plates on high-power GPUs to lower chip temperatures. |
| Rittal Rittal (Friedhelm Loh Group, Germany) · Company · Current · Facilities |
Racks, enclosures, in-row and rack cooling, and prefabricated modular data centres. | An edge site uses Rittal enclosed racks with built-in cooling. |
| nVent nVent Electric (NYSE: NVT) · Company · Current · Facilities |
Enclosures, cable management, electrical connections and liquid-cooling products including CDUs. | A data hall uses nVent cabinets with integrated liquid manifolds. |
| Panduit Panduit (private, USA) · Company · Current · IT |
Structured cabling, cable management, pathways, cabinets and rack PDUs. | Installers use Panduit overhead fibre pathways to route trunks between rows. |
| Amphenol (incl. former CommScope CCS) Amphenol (NYSE: APH) · Company · Current · IT |
Connector giant that bought CommScope's cabling business, including SYSTIMAX, for $10.5bn, closing January 2026. | Older SYSTIMAX-labelled copper and fibre is now supported by Amphenol. |
| Corning Corning (NYSE: GLW) · Company · Current · IT |
Major maker of optical fibre, cable and connectivity; AI clusters need far more fibre than traditional halls. | A GPU cluster uses Corning high-fibre-count cables to link thousands of switches. |
8.9 Careers I: Facilities, Engineering & Construction Roles
Behind every data centre is a team that keeps the power and cooling running 24 hours a day, plus the people who design and build new sites. These 'critical facilities' jobs suit people with electrical, mechanical or building skills, and many start as technicians. There is a well-known shortage of skilled staff, so good candidates are in demand.
Think of it like…
The facilities team is like the engineering crew on a ship: passengers (the IT) never see them, but without them the ship stops.
Real-world example
Fictional ex-electrician Priya joins a colocation site as a critical facilities technician on a four-on, four-off shift pattern. Her day starts with a handover, then a walk-round reading UPS, generator and chiller panels, followed by a planned task: assisting a vendor with a UPS battery test under an approved MOP. After two years and a certification she becomes a critical facilities engineer leading changes herself.
How it works
- Start as a technician or apprentice, learning rounds, alarms and safe working.
- Specialise in electrical, mechanical or controls systems.
- Lead maintenance and changes as an engineer, writing and executing MOPs.
- Move into shift lead, site operations manager, design, commissioning or construction roles.
- Senior paths include regional operations director or engineering design lead.
Who uses it
Electricians, HVAC technicians, military veterans, building-services and engineering graduates commonly move into these roles.
Key takeaway
Safety and procedure discipline matter more than knowing everything; say in interviews that you would stop and escalate rather than guess.
Going deeper
- Typical shift patterns include 4-on-4-off and other rotating 12-hour schedules covering nights, weekends and holidays; shift allowances and overtime are common in facilities roles.
- Qualification routes differ by country: US technicians usually need NFPA 70E training and may hold state electrical licences, while UK roles favour 18th Edition and authorised-person HV training.
- Progression usually depends on demonstrated MOP execution, incident handling and system knowledge; many employers run internal qualification levels for each electrical and mechanical system.
- Construction and commissioning roles boomed with AI campuses and often pay well but involve travel and project-to-project work, whereas operations roles offer more stability.
- The industry reports persistent staff shortages, so career-changers from the trades, the military and building services are actively recruited and trained.
- Useful early skills: reading single-line diagrams, understanding UPS and ATS operation, chilled-water basics, BMS alarm handling and writing clear shift handovers.
Common mistakes & misconceptions
- Overstating experience with high-voltage switching; employers check authorisation and will test your knowledge.
- Ignoring shift-work realities; nights, weekends and holidays are normal in operations roles.
- Chasing certificates before hands-on experience; employers value safe practical work first.
Try it: A sample technician shift checklist (YAML)
# shift_rounds.yaml - example of what a facilities round records
shift: day
handover_reviewed: true
rounds:
  - area: UPS room
    checks: [alarms_none, load_pct, battery_temp_c]
  - area: Generator yard
    checks: [block_heater_on, fuel_level_pct, no_leaks]
  - area: Chiller plant
    checks: [supply_temp_c, return_temp_c, pumps_running]
planned_work:
  - id: MOP-0423
    task: UPS battery test with vendor
    approval: change_board_approved
escalation_contact: shift_lead
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Critical facilities technician Colocation operators, hyperscalers, facilities contractors · Role · Current · Facilities |
Common first facilities job; employers look for a trade, military or apprenticeship background, safety training and willingness to work 24/7 shifts. | After two years of rounds, alarm response and assisting vendors, a technician earns a certification and is promoted to engineer. |
| Critical facilities engineer (CFE) Operators and hyperscalers · Role · Current · Facilities |
Mid-level step after technician or a trade career; needs deep electrical or mechanical knowledge, MOP-writing skills and calm incident leadership. | An ex-navy electrician joins as a CFE, qualifies on the site's switching procedures within six months, then starts leading changes. |
| Shift lead / chief engineer Operators · Role · Current · Operations |
Senior facilities step after several years as an engineer, adding people management, MOP approval and incident command. | A CFE who mentors new staff and handles incidents well becomes shift lead, then chief engineer of a 40 MW site. |
| Site / data centre operations manager Operators · Role · Current · Operations |
Leadership route for experienced engineers who add budgeting, customer, safety and people-management skills; often requires a degree or equivalent experience. | A chief engineer completes a management course and an operations certification before taking charge of a 60-person site. |
| Electrical engineer Operators, design firms, contractors · Role · Current · Electrical |
Designs or maintains HV/MV/LV systems, UPS, generators and protection settings. | Calculates breaker coordination for a new 2 MW hall extension. |
| Authorised / high-voltage electrician Operators and electrical contractors · Role · Current · Electrical |
Licensed electrician permitted to switch and maintain medium- and high-voltage equipment. | Performs switching under a permit-to-work to isolate a transformer for maintenance. |
| Mechanical engineer Operators, design firms · Role · Current · Mechanical |
Designs or maintains chillers, pumps, air handlers and liquid-cooling loops. | Rebalances chilled-water flows after a new liquid-cooled AI row is added. |
| Controls / BMS engineer Operators, controls integrators · Role · Current · Mechanical |
Programs and maintains the building management and power monitoring systems that automate plant. | Updates chiller sequencing logic so free cooling runs more hours a year. |
| Commissioning agent (CxA) Independent commissioning firms · Role · Current · Facilities |
Specialist career testing new systems from factory witness tests to integrated tests; suits engineers who enjoy travel, deadlines and fault-finding. | A former facilities engineer joins a commissioning firm and spends a year scripting and running Level 4 and 5 tests on AI campuses. |
| MEP design engineer Engineering consultancies · Role · Current · Facilities |
Office-based design career, usually needing an engineering degree and later professional registration, working on calculations, drawings and BIM models. | A graduate engineer models cooling loads in her first year and becomes electrical lead for a 30 MW building five years later. |
| Construction / project manager General contractors, developers, hyperscalers · Role · Current · Business |
Career for construction, engineering or project-management graduates; the AI building boom has created strong demand for people who deliver on schedule. | A site engineer from hospital projects moves to data centres and soon manages long-lead deliveries for a 100 MW campus. |
| EHS manager Operators and contractors · Role · Current · Operations |
Safety career needing qualifications such as NEBOSH or OSHA training plus site experience; enforces permits, arc-flash rules and contractor safety. | A construction safety adviser moves to a data-centre campus and introduces arc-flash PPE audits after a near miss. |
| Security officer / security operations Operators and security firms · Role · Current · Security |
Entry route needing a security licence where required, attention to detail and procedure discipline; can lead to security operations management. | An officer who masters the access-control system moves into the security operations centre, then becomes site security manager. |
| Vendor field service engineer UPS, generator and cooling manufacturers · Role · Current · Electrical |
Manufacturer career for technicians with electrical or HVAC skills, offering factory training, travel and deep knowledge of one product family. | A UPS field engineer covers twenty data centres in a region, then later joins an operator's engineering team. |
8.10 Careers II: IT, Operations & Business Roles
Not every data-centre job involves generators and chillers. Many people work with the servers, network cables and software inside, while others plan capacity, sell space, manage energy or choose new sites. AI clusters have added new roles for people who can build and run huge GPU systems.
Think of it like…
If facilities staff keep the stadium's lights and turf in shape, these roles are the players, coaches, ticket office and stadium planners.
Real-world example
Fictional graduate Tomás starts as a data centre technician at a cloud provider, swapping failed drives, replacing memory and running fibre patches from work tickets. He learns Linux and networking in the evenings and earns a networking certification. Two years later he moves into a deployment engineer role, bringing new GPU racks online, and later becomes an AI cluster engineer.
How it works
- Start in a hands-on technician, NOC or cabling role.
- Learn Linux, networking and a scripting language such as Python.
- Specialise: networking, deployment, capacity, DCIM, AI/HPC or sustainability.
- Business-minded people move into sales engineering, account management or site selection.
- Senior roles include data centre architect, infrastructure manager or head of capacity.
Who uses it
IT support staff, computer-science and networking students, career changers and business graduates all find routes in here.
Key takeaway
Data centre technician jobs at cloud providers are a common first step for beginners; list hands-on lab work and any safety training on your CV.
Going deeper
- Hyperscale technician roles often involve high-volume break-fix work driven by tickets and automated diagnostics, while colocation roles involve more customer contact and remote-hands requests.
- Linux, basic networking (VLANs, BGP, optics), scripting in Python or Bash and server-management interfaces such as BMC, IPMI and Redfish are the skills that unlock promotion.
- AI cluster roles add GPU health checks, InfiniBand or RoCE fabric troubleshooting, cabling at massive scale and job schedulers such as Slurm or Kubernetes.
- Business roles still need technical literacy: sales engineers, capacity planners and site-selection managers must read single-line diagrams, density figures and lease terms.
- Sustainability and energy roles now need regulatory knowledge, such as EU reporting, CSRD and the GHG Protocol, alongside metering and data-analysis skills.
Common mistakes & misconceptions
- Ignoring the physical side; technician roles involve lifting, standing for long periods and shift work.
- Neglecting documentation; accurate tickets and asset records are judged as closely as technical fixes.
- Assuming business roles need no technical knowledge; credibility with customers depends on it.
Try it: Read your own machine's hardware like a DC technician (Linux, run as admin on your own PC)
lscpu                           # CPU model, cores, sockets
sudo dmidecode -t memory | less # memory modules and slots
lsblk -o NAME,SIZE,MODEL        # disks
sudo smartctl -H /dev/sda       # disk health (smartmontools)
sudo ipmitool sdr list          # sensors, only on servers with a BMC
nvidia-smi                      # GPU status, if you have an NVIDIA GPU
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Data centre technician Hyperscalers, colocation operators, server makers · Role · Current · IT |
The most common beginner route into IT-side data-centre work; employers want basic hardware, networking and Linux skills plus reliability on shifts. | A helpdesk worker with CompTIA A+ is hired as a technician, then moves into deployment engineering after eighteen months. |
| Deployment / rack-and-stack engineer Cloud providers, neoclouds, integrators · Role · Current · IT |
Installs, cables, powers and tests new racks and clusters before customers use them. | Brings 40 GPU racks online in a week, running burn-in tests and fixing cabling errors. |
| Structured cabling / fibre installer Cabling contractors · Role · Current · IT |
Installs, terminates, labels and tests copper and fibre cabling between racks and rooms. | Splices and tests 1,000 fibres for a new AI cluster's network. |
| NOC operator / monitoring analyst Operators, network providers · Role · Current · Operations |
Entry route for people with IT support or monitoring experience, leading to incident management, network or reliability engineering roles. | A NOC operator who writes clear incident reports and learns scripting moves into a reliability engineering team. |
| Network engineer Operators, clouds, enterprises · Role · Current · IT |
Career path from technician or NOC roles via networking certifications; senior engineers design fabrics, automate configuration and plan interconnection. | A cabling technician studies for a networking certification, joins the network team and two years later designs a new spine-leaf fabric. |
| AI cluster / HPC engineer Neoclouds, AI labs, hyperscalers · Role · Emerging · IT |
Builds and runs large GPU clusters, their high-speed networks, schedulers and health checks. | Finds a bad optical link slowing a 4,000-GPU training job and swaps it. |
| Capacity planner Operators and hyperscalers · Role · Current · Operations |
Tracks space, power and cooling use and forecasts when more capacity is needed. | Warns that a hall will be 95% power-committed in eight months, triggering a new build. |
| DCIM analyst Operators and enterprises · Role · Current · Operations |
Keeps the DCIM database of assets, power and connections accurate and builds reports. | Audits a hall and corrects 120 wrong rack locations in the system. |
| Data centre architect / solutions architect Operators, vendors, consultancies · Role · Current · IT |
Designs how IT, power, cooling and network fit together for a customer or new site. | Designs a 2 MW liquid-cooled suite layout for a customer's AI cluster. |
| Sustainability / energy manager Operators and hyperscalers · Role · Current · Sustainability |
Growing career for engineering or environmental graduates, combining energy data, carbon accounting, regulation and power procurement. | An energy analyst from a utility moves into a colocation sustainability role, handling EU reporting and a solar PPA. |
| Site selection / real-estate manager Hyperscalers, developers, brokers · Role · Current · Business |
Finds and secures land, power and permits for new data centres. | Compares five sites on grid timelines, fibre, tax incentives and flood risk. |
| Sales engineer Operators and equipment vendors · Role · Current · Business |
Career for technically strong people who enjoy customers, often after design or operations roles; designs solutions and answers technical questions. | A former facilities engineer becomes a sales engineer, explaining 2N power and liquid-cooling options to AI tenants. |
| Customer success / account manager Colocation operators · Role · Current · Business |
Business career managing existing colocation customers; suits people with customer-service, IT or data-centre operations backgrounds. | A remote-hands technician moves into account management, handling renewals and expansions for twenty enterprise customers. |
| Energy & power procurement manager Hyperscalers and large developers · Role · Emerging · Business |
Negotiates grid connections, power contracts and on-site generation deals. | Agrees a 15-year contract for power from a new wind farm plus a gas peaker for backup. |
8.11 Certifications & Training That Employers Recognise
Certifications are courses with exams that prove you know a subject to a recognised level. In data centres, some cover the whole facility, some cover design standards or cabling, and some cover the IT inside. Safety and electrical qualifications are often legally required before you may touch certain equipment.
Think of it like…
Certifications are like a driving licence plus extra endorsements: the basic licence gets you on the road, and endorsements let you drive bigger vehicles.
Real-world example
Fictional student Amara plans her first year: CompTIA A+ in three months, then an entry data centre course such as CDCP or CDCTP while applying for technician jobs. After landing a job, her employer pays for NFPA 70E safety training and later an operations course. She keeps a spreadsheet of exam dates, costs and renewal deadlines.
How it works
- Start with fundamentals: A+, Network+ or an entry data-centre course.
- Add mandatory safety training for your country and role.
- Choose a specialist path: operations, design, cabling, electrical or AI infrastructure.
- Let employers fund expensive courses once you are hired.
- Track renewals; many certifications expire after a few years.
Who uses it
Job seekers, technicians aiming for promotion, engineers moving into design, and managers proving competence to customers and auditors.
Key takeaway
A cheap fundamentals certificate plus hands-on experience beats an expensive design credential you cannot yet use; always check the current exam code before booking.
Going deeper
- Entry certificates such as CompTIA A+, Network+, CDCP and CDCTP show vocabulary and commitment; they rarely replace experience but help CVs pass automated screening.
- Uptime Institute's ATD, ATS and AOS are aimed at professionals working with Tier certification, so most people take them once employed, often with employer funding.
- BICSI credentials (Installer, Technician, RCDD, DCDC) are respected in cabling and design; RCDD requires qualifying industry experience before you can sit the exam.
- Safety training is often a legal or contractual prerequisite: NFPA 70E and OSHA Outreach cards in the US, and electrical qualifications such as the 18th Edition in the UK.
- Vendor and AI certifications from NVIDIA, cloud providers and network vendors signal skills for GPU and network roles; exam codes and validity periods change often.
Common mistakes & misconceptions
- Paying for expensive design certifications before you can use them; start with fundamentals and safety.
- Letting certifications lapse; many require periodic renewal, fees or continuing-education credits to stay valid.
- Booking outdated exam versions; check current exam codes on the provider's website first.
Try it: A 12-month study plan (YAML)
# study_plan.yaml - example beginner route
months_1_3:
  - CompTIA A+ (Core 1 and Core 2)
  - Read: power chain, cooling basics, PUE
months_4_6:
  - Entry data-centre course (e.g. CDCP or CDCTP)
  - Home lab: Linux server, smartctl, ipmitool on an old server
months_7_9:
  - CompTIA Network+ or Server+
  - Safety: local electrical-safety / OSHA 10 type training
months_10_12:
  - Apply for technician roles; keep a learning log
  - Optional: NVIDIA NCA-AIIO for AI infrastructure basics
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| CDCP (Certified Data Centre Professional) EPI (Enterprise Products Integration) · Certification · Current · General |
Popular two-day entry course covering data-centre power, cooling, fire, security and standards. | A new technician takes CDCP in her first month to learn the vocabulary of the whole facility. |
| CDCS / CDCE EPI · Certification · Current · General |
Certified Data Centre Specialist and Expert: follow-on courses going deeper into design and operations. | An engineer moves from CDCP to CDCS before joining a design review team. |
| CDFOM EPI · Certification · Current · Operations |
Certified Data Centre Facilities Operations Manager: focuses on running operations, maintenance and staff. | A new shift lead takes CDFOM to learn maintenance planning and operations management. |
| Accredited Tier Designer (ATD) Uptime Institute · Certification · Current · Facilities |
Teaches designers how to meet Uptime Tier requirements; aimed at experienced engineers. | An electrical design engineer earns ATD before leading a Tier III design submission. |
| Accredited Tier Specialist (ATS) Uptime Institute · Certification · Current · Operations |
Explains the Tier Standard for people who operate, manage or buy Tier-certified sites. | An operations manager takes ATS to understand what Tier III means for maintenance. |
| Accredited Operations Specialist (AOS) Uptime Institute · Certification · Current · Operations |
Covers operational sustainability: staffing, maintenance, procedures and risk management. | A site manager earns AOS while preparing for an operations assessment. |
| CDCTP (Certified Data Centre Technician Professional) CNet Training (an Uptime Education company) · Certification · Current · IT |
Technician-level qualification covering data-centre infrastructure and practical skills. | An IT support worker completes CDCTP to switch into a data centre technician role. |
| CDCDP (Certified Data Centre Design Professional) CNet Training (an Uptime Education company) · Certification · Current · Facilities |
Design-focused qualification covering planning, power, cooling and standards. | A consultant takes CDCDP before designing a client's on-site server room. |
| RCDD BICSI · Certification · Current · IT |
Registered Communications Distribution Designer: respected credential for designing structured cabling systems. | A cabling designer with RCDD signs off fibre pathways for a new campus. |
| DCDC (Data Center Design Consultant) BICSI · Certification · Current · Facilities |
BICSI credential for designing data-centre infrastructure, based on the ANSI/BICSI 002 standard. | A design consultant earns DCDC to strengthen bids for data-centre projects. |
| BICSI Installer & Technician BICSI · Certification · Current · IT |
Hands-on cabling credentials: Installer 1, Installer 2 (copper or optical fibre) and Technician. | A fibre installer progresses from Installer 2 Optical Fiber to Technician. |
| CompTIA A+ and Network+ CompTIA (A+ 220-1201/1202; Network+ N10-009) · Certification · Current · IT |
Vendor-neutral entry certifications for hardware, operating systems and networking. | Many technician job adverts list A+ or Network+ as preferred. |
| CompTIA Server+ CompTIA (SK0-005) · Certification · Current · IT |
Covers server hardware, storage, installation and troubleshooting; check for newer exam versions before booking. | A technician earns Server+ to prove server hardware skills. |
| NVIDIA AI infrastructure certifications NVIDIA (NCA-AIIO associate; NCP-AII, NCP-AIO, NCP-AIN professional) · Certification · Emerging · IT |
Exams on AI infrastructure, operations and networking for GPU clusters. | A deployment engineer earns NCA-AIIO before moving onto an AI cluster team. |
| NFPA 70E & OSHA 10/30 training NFPA (USA); OSHA Outreach Training Program · Certification · Current · Electrical |
Electrical-safety (arc flash, PPE) and general workplace-safety training expected on US sites. | A new US technician completes NFPA 70E qualified-person training before any electrical work. |
| Electrician licences & BS 7671 US state licensing boards; UK IET/BSI BS 7671 (18th Edition) · Certification · Current · Electrical |
Formal electrical qualifications: US journeyman/master licences; in the UK, training on the IET Wiring Regulations. | A UK electrician completes an 18th Edition course before joining a data-centre contractor. |
8.12 Learning Resources, News & Communities
The data-centre industry changes every month, so professionals keep learning through news sites, research reports, free vendor courses and industry groups. Many of the best resources are free. Joining communities and attending local events is also the fastest way to meet people who hire.
Think of it like…
Building your learning routine is like going to the gym: a little reading every week beats cramming once a year.
Real-world example
Fictional career-changer Jordan sets a weekly routine: 20 minutes of trade news every morning, one vendor white paper each weekend and one recorded conference talk on Wednesdays. He posts questions on an online forum and attends a local chapter meeting of an industry association. Three months later a member he met there refers him for a technician vacancy.
How it works
- Follow two or three trade-news sources for daily headlines.
- Read annual surveys to understand big trends and statistics.
- Work through free vendor courses and white papers on power and cooling.
- Watch conference talks to see how leading operators design sites.
- Join a community or association and attend events to build contacts.
Who uses it
Students, job seekers and experienced engineers alike; hiring managers often ask what you read to stay current.
Key takeaway
Mention one recent industry story and one survey statistic in an interview to show genuine interest.
Going deeper
- Uptime Institute's annual surveys provide citable statistics on outages, PUE, staffing and rack density; read the free summaries and note one figure to use in interviews.
- Schneider Electric's white papers and free online courses explain UPS topologies, containment, economisers and total cost of ownership in an accessible style, making them ideal first reading.
- Trade news from DCD, Data Center Frontier and Data Center Knowledge shows who is building where, which helps you target applications at companies that are hiring.
- Associations such as 7x24 Exchange and AFCOM run local chapters and student or young-professional events, often the fastest way to meet hiring managers.
- Listed operators' filings and investor presentations are free, detailed and reliable sources on capacity, pricing and strategy.
Common mistakes & misconceptions
- Relying on social-media rumours; verify claims with primary sources such as filings and official announcements.
- Only reading and never building notes or labs; employers want evidence you applied what you learned.
- Paying for courses before using the free vendor and association material.
Try it: A weekly learning routine you can copy (YAML)
# learning_routine.yaml
daily:   {minutes: 20, source: 'one trade-news site'}
weekly:
  - one vendor white paper (power or cooling)
  - one conference talk recording
  - write 5 lines in a learning log: what I learned, one question
monthly:
  - attend a local meetup or association chapter event
  - review one annual industry survey chart
quarterly:
  - book or renew one certification
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Uptime Institute research & annual survey Uptime Institute · Resource · Current · General |
Publishes an annual global data-centre survey plus outage analyses and research on staffing, power and cooling. | Students quote the survey's findings on outage causes and staffing shortages in interviews. |
| DCD (DatacenterDynamics) DCD (publisher and events company) · Resource · Current · General |
Major trade news site, magazine and event organiser covering deals, builds and technology worldwide. | Read DCD daily to follow new campus announcements and acquisitions. |
| Data Center Frontier Trade publication · Resource · Current · General |
News and long-form features on data-centre design, AI campuses, power and cooling. | A student reads its features on liquid cooling before an interview. |
| Data Center Knowledge Trade publication · Resource · Current · General |
Long-running trade news site covering operations, design, hardware and industry business. | Use its explainers to learn terms quickly before a site tour. |
| The Register (data centre coverage) The Register (UK tech news) · Resource · Current · IT |
Technology news site with frequent, often irreverent coverage of data centres, chips and AI infrastructure. | Follow its reporting on GPU systems and hyperscaler spending. |
| SemiAnalysis SemiAnalysis (independent research, mostly paid) · Resource · Current · Business |
Deep research on AI chips, data-centre power and AI infrastructure economics; some articles are free. | An analyst reads its free posts to understand AI cluster power and cooling needs. |
| Schneider Electric white papers Schneider Electric Energy Management Research Center · Resource · Current · Electrical |
Large free library of vendor-neutral-style white papers and calculators on power, cooling and efficiency. | Read its papers on UPS topologies and containment before your first facilities job. |
| ASHRAE Datacom Series ASHRAE Technical Committee 9.9 · Resource · Current · Mechanical |
Book series on data-centre thermal guidelines, liquid cooling, power and design. | Mechanical engineers keep 'Thermal Guidelines for Data Processing Environments' on their desk. |
| Open Compute Project (OCP) Summit talks Open Compute Project Foundation · Resource · Current · IT |
Free recorded summit talks in which hyperscaler and vendor engineers explain real rack, power and cooling designs; excellent self-study material. | Watch OCP talks on liquid-cooled AI racks to see real hyperscaler designs. |
| 7x24 Exchange 7x24 Exchange International · Organisation · Current · Facilities |
Association for mission-critical facilities professionals, with conferences and local chapters. | A student volunteers at a chapter event and meets three site managers. |
| AFCOM & Data Center World AFCOM (association) and the Data Center World conference · Organisation · Current · Operations |
Professional association for data-centre and facilities managers with chapters and an annual conference. | Attend a regional chapter meeting to hear operators discuss staffing and AI loads. |
| iMasons (Infrastructure Masons) Infrastructure Masons (non-profit) · Organisation · Current · General |
Global community of digital-infrastructure professionals running education, diversity and climate programmes. | Attend its events and online sessions to meet experienced infrastructure professionals and learn about industry programmes. |
| Reddit r/datacenter Online community · Resource · Current · General |
Forum where technicians and engineers share career advice, photos and day-to-day questions. | Search it for real accounts of technician interviews and shift patterns. |
| Microsoft Datacenter Academy Microsoft with community colleges · Resource · Current · General |
Programme partnering with local colleges near Microsoft datacentres to train students for technician careers. | A college student completes the programme's courses and gets a datacentre internship. |
| Free vendor training e.g. Schneider Electric Energy University, Vertiv Academy, NVIDIA DLI · Resource · Current · General |
Online and in-person courses from manufacturers on their products and on data-centre basics. | Complete free online power and cooling modules and list them on your CV. |
| Podcasts & video channels Trade publishers, vendors and independent creators · Resource · Current · General |
Interviews, site tours and explainers that make complex topics easy to absorb on the go. | Listen to an industry podcast during your commute to hear how operators solve power shortages. |
8.13 Interview Questions & How to Break In
Most data-centre interviews mix technical questions about power, cooling and safety with questions about how you behave under pressure. You do not need years of experience to start, but you must show safe habits, curiosity and the basics. Many people enter from the military, the electrical or HVAC trades, or IT helpdesk jobs.
Think of it like…
An interview is like a driving test: they want to see you know the rules of the road and stay calm, not that you can race.
Real-world example
Fictional candidate Leila is asked: 'The utility fails at 3 a.m. — what happens?' She explains: UPS batteries carry the IT load instantly, generators start and stabilise within seconds, the ATS transfers load to them, and the team follows the emergency procedure and logs everything. She adds she would never bypass a step without the shift lead. The interviewer later says that last sentence won her the job.
How it works
- Revise the core concepts: power chain, redundancy, PUE, airflow and safety.
- Prepare three STAR stories about problem-solving, teamwork and following procedure.
- Build a small home lab and keep a learning log or portfolio.
- Apply widely to technician, NOC and cabling roles; tailor your CV to each.
- After the interview, follow up and keep studying whatever you could not answer.
Who uses it
Anyone applying for technician, engineer or operations roles, and interviewers preparing questions.
Key takeaway
When unsure, say what you would check and who you would escalate to; data-centre employers value safe caution over confident guessing.
Going deeper
- Technical interviews often include a whiteboard power-chain drawing, a utility-failure scenario, redundancy definitions and a PUE calculation; practise each aloud in under two minutes.
- Behavioural questions test safety culture: describe a time you stopped work, escalated a concern or followed a procedure under pressure, using the STAR structure.
- A portfolio with a simple 2N single-line diagram, a home-lab write-up and notes from a vendor course gives interviewers concrete evidence beyond the CV.
- Veteran, trade and helpdesk routes are recognised entry paths; translate past experience into data-centre language, such as 'maintained generators' or 'worked to written procedures'.
- Large employers run structured hiring with online assessments and panel interviews; read the job description's required skills and reflect its wording honestly in your CV.
Common mistakes & misconceptions
- Guessing when unsure; say what you would check and who you would escalate to.
- Leaving safety out of answers; mention LOTO, PPE and MOPs whenever you describe hands-on work.
- Sending one generic CV everywhere; tailor it to technician, NOC or cabling roles.
Try it: Practise the classic interview maths: PUE and downtime per year
# Python: two numbers interviewers love
facility_kw, it_kw = 1300, 1000
print('PUE =', facility_kw / it_kw)            # 1.3

for availability in (99.9, 99.99, 99.999):
    minutes = (1 - availability / 100) * 365 * 24 * 60
    print(f'{availability}% -> {minutes:.1f} minutes down per year')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Q: Explain N, N+1 and 2N Classic technical question · Concept · Current · General |
N is just enough capacity; N+1 adds one spare unit; 2N duplicates the whole system on two independent paths. | Answer with an example: four chillers needed, five installed is N+1; two full UPS systems is 2N. |
| Q: What is PUE? The Green Grid; ISO/IEC 30134-2 · Metric · Current · Sustainability |
Total facility energy divided by IT energy; lower is better and 1.0 is the theoretical ideal. | 1,300 kW facility for 1,000 kW of IT gives PUE 1.3; mention it is measured over a year. |
| Q: Walk me through the power chain Classic technical question · Practice · Current · Electrical |
Trace power from grid to chip: utility, substation, transformer, switchgear, UPS, PDU, RPP, rack PDU, server PSU. | Draw it on a whiteboard and add where generators and the ATS connect. |
| Q: What happens when the utility fails? Classic scenario question · Procedure · Current · Electrical |
UPS carries load instantly, generators start, ATS transfers, cooling restarts, staff follow the EOP and log events. | Mention you would check generators are carrying load, fuel levels and UPS battery recharge afterwards. |
| Q: Hot vs cold aisle containment Classic technical question · Concept · Current · Mechanical |
Containment physically separates cold supply air from hot exhaust so they do not mix, improving efficiency. | Explain that cold-aisle containment encloses the inlet aisle while hot-aisle containment captures the exhaust. |
| Q: What are a MOP, SOP and EOP? Operations procedures · Document · Current · Operations |
Method of Procedure for a specific change; Standard Operating Procedure for routine tasks; Emergency Operating Procedure for failures. | Say you follow a MOP line by line, with a second person checking, and stop if anything differs. |
| Q: LOTO and arc flash OSHA 1910.147; NFPA 70E · Procedure · Current · Electrical |
Lockout/tagout isolates and locks energy sources; arc flash is a violent electrical explosion that PPE and de-energising prevent. | Explain you would verify zero energy with a tested meter before touching any conductor. |
| STAR behavioural answers Interview technique · Practice · Current · General |
Answer behavioural questions with Situation, Task, Action and Result, keeping each story under two minutes. | 'Tell me about a mistake': describe a missed step, how you reported it and the checklist you then created. |
| Home lab Self-study · Practice · Current · IT |
A small set-up at home, such as an old server or Raspberry Pi, to practise Linux, monitoring and cabling. | Install Linux on a used server, read its sensors with ipmitool and graph temperatures. |
| Learning portfolio Self-study · Resource · Current · General |
A simple online log or document showing labs, certifications, diagrams and notes you have produced. | Share a one-page drawing of a 2N power design and a write-up of your home lab. |
| Military veteran route Employer veteran programmes · Practice · Current · General |
Veterans with electrical, mechanical or IT experience are highly valued for discipline and procedure-following. | A former navy electrician moves into a critical facilities engineer role within months. |
| Trades route Electricians, HVAC and building-services technicians · Practice · Current · Facilities |
Qualified tradespeople can move straight into facilities roles after learning data-centre specifics. | An HVAC technician joins a site's mechanical team and learns chillers and CRAHs. |
| IT helpdesk route IT support and NOC roles · Practice · Current · IT |
Helpdesk experience with hardware, tickets and customers maps well to data centre technician work. | A helpdesk analyst with A+ applies for a cloud provider's technician role. |
| Apprenticeships & college programmes Employers, colleges and government schemes · Resource · Current · General |
Paid apprenticeships and college partnerships train beginners while they work toward qualifications. | A school leaver joins a two-year data-centre engineering apprenticeship with a colocation operator. |
| Q: Tier III vs Tier IV? Classic technical question · Concept · Current · General |
Tier III is concurrently maintainable: any component can be maintained without shutdown. Tier IV also survives any single unplanned failure. | Add that Tier IV usually needs active 2N paths with compartmentalisation, and that neither Tier guarantees zero downtime. |
| Q: Why do AI racks need liquid cooling? Modern technical question · Concept · Emerging · Mechanical |
Racks of 100 kW or more produce more heat than air can practically remove; liquid carries far more heat per volume directly from chips. | Mention cold plates, CDUs and facility water loops, and that a GB200 NVL72 rack draws roughly 120-140 kW. |
8.14 Industry Trends to Watch (2026 and Beyond)
AI has turned data centres from quiet back-office buildings into one of the world's biggest construction and energy stories. Racks are getting far more power-hungry, liquid cooling is becoming normal and finding electricity is now the hardest part of any project. Some ideas, like data centres in space, are still experiments.
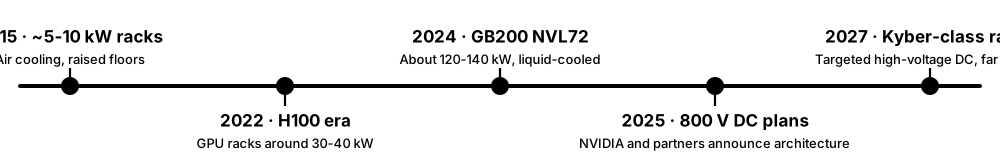
Think of it like…
The industry is like a city that suddenly needs ten times more water: plumbing, reservoirs and rules all have to change at once.
Real-world example
Fictional operator Ironbridge planned its 2022 halls for 10 kW racks with air cooling. By 2026 a customer asks for 130 kW AI racks, so Ironbridge retrofits one hall with CDUs and liquid loops and designs its next building for 200 kW+ racks. Because the grid connection is years away, it adds on-site gas generation and a battery system, and signs a long-term clean-power contract.
How it works
- Track rack densities in new GPU systems and their power and cooling needs.
- Watch how utilities, regulators and governments respond to huge new loads.
- Follow energy deals: gas, nuclear, renewables, storage and fuel cells.
- Note which technologies move from 'emerging' to standard practice.
- Separate firm, funded projects from announcements and speculation.
Who uses it
Everyone in the industry, especially designers, investors, energy managers and job seekers choosing which skills to learn.
Key takeaway
Liquid cooling, high-voltage power distribution and grid/energy skills are the safest bets for a future-proof career.
Going deeper
- Density drives everything: higher kW per rack changes floor loading, distribution voltages, cooling technology and the skills operators need on every shift.
- Energy has become strategic: developers sign gas, nuclear, geothermal and storage deals and some build on-site plants, so energy-market knowledge is a career differentiator.
- Regulation and community scrutiny are rising together, with large-load tariffs, water and noise rules and reporting duties shaping where and how campuses are built.
- Supply chains for GPUs, high-bandwidth memory, transformers and turbines can delay projects more than construction itself, making procurement and planning key roles.
- Speculative ideas such as orbital data centres attract headlines; separate funded, under-construction projects from announcements when judging which trends will create jobs.
Common mistakes & misconceptions
- Treating every announcement as certain; many projects are delayed, resized or cancelled.
- Assuming air-cooling skills are obsolete; most general-purpose IT will remain air-cooled for years.
- Ignoring energy and policy trends; they increasingly decide where data centres, and jobs, appear.
Try it: How much coolant does a 130 kW AI rack need? (worked example)
# Python: coolant flow = heat / (specific heat x temperature rise)
heat_w = 130_000          # rack heat load, W
cp = 4186                 # J/(kg.K), water (glycol mixes are lower)
delta_t = 10              # K temperature rise across the rack
kg_per_s = heat_w / (cp * delta_t)
print(f'{kg_per_s:.2f} kg/s = about {kg_per_s*60:.0f} litres per minute')
Key equipment, standards, metrics, vendors & tools
| Name | What it does | Example |
|---|---|---|
| Rising AI rack density NVIDIA and other accelerator makers · Concept · Emerging · IT |
Trend: rack power keeps climbing past 120-140 kW towards several hundred kW, making density planning a core skill in design and operations. | Job adverts increasingly ask for experience with high-density or liquid-cooled deployments, even for technician posts. |
| 800 V DC power distribution NVIDIA and power-equipment partners (announced 2025) · Technology · Emerging · Electrical |
Trend: AI halls are expected to move towards high-voltage DC distribution from about 2027, needing new equipment, safety rules and DC-qualified staff. | Electrical engineers who learn DC protection and DC arc-flash practices will be in demand as vendors launch products. |
| Liquid cooling goes mainstream Industry-wide · Concept · Emerging · Mechanical |
Direct-to-chip liquid cooling is standard for new AI deployments; air remains for general IT. | New AI halls are designed with CDUs and liquid loops from day one rather than retrofitted. |
| Behind-the-meter generation Operators, turbine and fuel-cell makers · Practice · Emerging · Electrical |
Trend: AI campuses increasingly bring their own power with gas turbines, engines, fuel cells and batteries, blurring data-centre and power-plant work. | Operators recruit power-plant engineers to run on-site generation at campuses waiting years for full grid connections. |
| Large-load grid rules State regulators and grid operators · Regulation · Emerging · Business |
Trend: regulators are writing special rules for very large loads, covering who pays for upgrades, minimum usage commitments and curtailment. | Energy-policy literacy is becoming a valued skill as more states and countries follow early examples such as Texas and Ohio. |
| Sovereign AI Governments worldwide · Concept · Emerging · Business |
Countries funding domestic AI data centres so sensitive data and AI capability stay under national control. | The EU's InvestAI initiative (2025) earmarked about €20bn for AI 'gigafactories'. |
| Prefabrication & modular builds Equipment vendors and contractors · Practice · Current · Facilities |
Power rooms, cooling skids and even whole halls built in factories and assembled on site to save time. | A developer installs factory-built electrical skids, cutting months off the schedule. |
| Community & water scrutiny Local residents, councils, regulators · Concept · Current · Sustainability |
Growing local opposition over noise, water, land, electricity prices and air quality from on-site generators. | A county pauses data-centre approvals to review water and noise rules. |
| Chip and memory supply costs Semiconductor and memory makers · Concept · Current · IT |
Shortages of GPUs, high-bandwidth memory and DRAM raised AI infrastructure costs in 2025-26. | A neocloud delays a cluster because memory-heavy servers cost more than budgeted. |
| Workforce shortage Uptime Institute surveys and industry bodies · Concept · Current · Operations |
Operators consistently report difficulty hiring and keeping qualified staff, creating opportunities for newcomers. | Employers launch apprenticeships and veteran programmes to fill technician gaps. |
| Orbital data centres Startups such as Starcloud; Google research (Project Suncatcher) · Concept · Emerging · General |
Speculative idea of computing in orbit using constant solar power; early prototypes only. | Treat it as an experiment to watch, not a career plan, as of 2026. |
| Underwater data centres Microsoft Project Natick (ended 2024); Shenzhen HiCloud (Hainan, China) · Concept · Emerging · General |
Sealed server capsules on the seabed cooled by seawater; Microsoft ended its trials in 2024, while a commercial subsea site operates off Hainan. | Natick's Orkney capsule had one-eighth the server failure rate of land sites, yet Microsoft judged subsea building impractical at scale. |
| AI capex sustainability debate Investors, analysts and company filings · Concept · Emerging · Business |
Debate over whether AI revenues will justify record infrastructure spending, which affects how long the building boom lasts. | Analysts watch hyperscaler earnings calls for signs of slower spending, which would ripple through construction and equipment orders. |
| Mega-deals and consolidation Infrastructure funds, sovereign investors and operators · Concept · Current · Business |
Data-centre platforms are changing hands in record deals, concentrating capacity among a few large, well-funded owners. | The roughly $40bn purchase of Aligned Data Centers, completed in 2026, became the largest data-centre deal so far. |
| Inference growth AI providers and industry analysts · Concept · Emerging · IT |
As AI use grows, more compute serves live user requests rather than training, favouring capacity closer to users and population centres. | An operator plans smaller liquid-cooled inference halls in city markets alongside its remote training campuses. |